Sunday Edition: 25th October
Published 25-OCT-2026 17:16 P.M.
|
19 minute read
Disclosure: S3 Consortium Pty Ltd and its associated entities may hold direct or indirect interests in securities referred to in this publication and may receive fees or other forms of consideration from entities mentioned. These interests and arrangements may create a potential conflict of interest in the preparation of this material.
The information contained in this communication is provided for general information purposes only and may relate to speculative investments. It does not constitute financial product advice, and has been prepared without taking into account your personal objectives, financial situation or needs. You should consider obtaining independent financial advice before making any investment decision.
Any forward-looking statements are uncertain and not a guaranteed outcome.
Below you can find short overviews of all the content we published last week, plus links to each full note.
Further down, there’s also some links to other interesting stuff we came across on our travels around the internet.
Yesterday’s Saturday note: Small caps just had their Red Wedding (Jim Chalmers sends his regards)
Quick Takes: IVZ, ILA, OD6, BUY, VKA, LKY, TRI, PNN, BPM, NS1
Deep Dives: PNN, RCM, PKP, LSR, MNB
Other content: AW1, CAY, ILA, OD6, IVR, AL3, BUY, PNN, RCM, NS1, LSR, AVM, IVZ, PAT, PKP, LKY
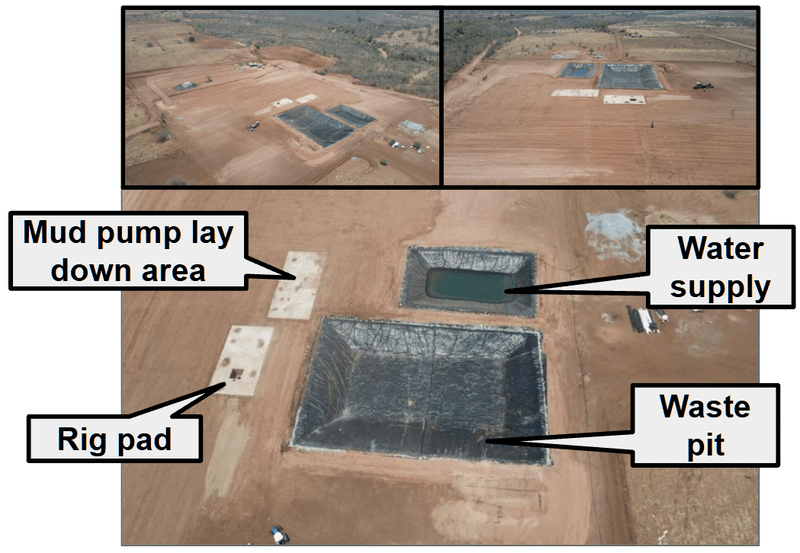
IVZ's rig is on the move to its 1.2 Tcf gas + 73M barrel condensate target - drilling in November.
This will be the first well IVZ has drilled since its discovery in 2022-23, which was labelled the second largest discovery in Sub-Saharan Africa for 2023.
The Musuma Prospect is one of ~12 prospects on a project with a combined ~5.5 billion barrels of oil equivalent in prospective resources (unrisked).
This upcoming well is a lot shallower than IVZ’s previous two (~1,500m target depth versus ~3,360m) - hopefully that means things are cheaper and less technically risky.
IVZ started moving the rig to site this week - drilling is planned for November.
(source)
ILA completed screening for its USAMRIID Marburg disease study.
ILA is set to soon start its non-human primates study for a safe and effective treatment for Marburg virus - a Category A bioterrorism threat with no current approved vaccine or treatment.
ILA has now completed screening of 22 primates for a dose optimisation study.
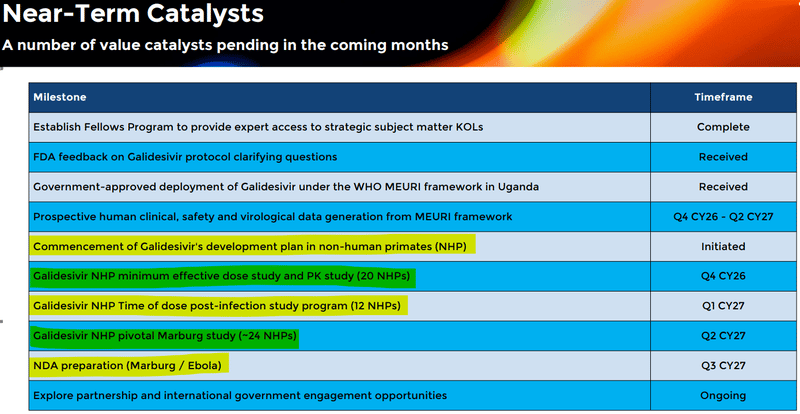
The upcoming study will be where ILA will establish which dose size/timing is likely to be the most effective, before ILA moves to its pivotal efficacy study.
Dosing for the optimisation study is expected to start before the end of the year.
Below is ILA’s most up to date timeline guidance - highlighted yellow is what is still to come:
(source)
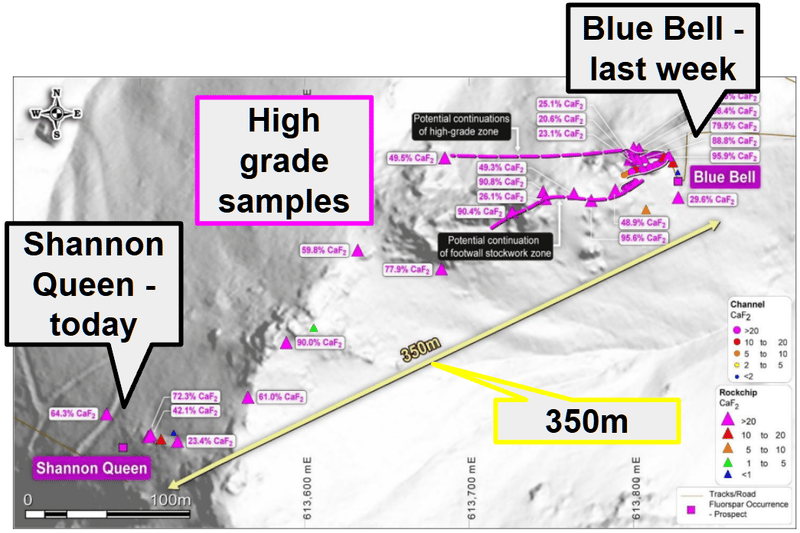
OD6 extended the high grade corridor on its Nevada critical minerals project by 350m.
Last week OD6 announced a brand new high grade target called Blue Bell, around 12km south of its main target area.
This week's sampling extended that target along a ~350m trend, with grades up to 95.6% fluorspar.
OD6 has been surface sampling its US fluorspar project while it waits for drill permits to arrive.
OD6 is planning to start drilling its main targets in early 2027 - we are keeping an eye on when these permits come in.
(source)
BUY - Offshore Liberia Investor Presentation.
This week BUY released its first investor presentation since it signed a binding agreement to acquire the exclusive right to negotiate a PSC over an offshore Liberia block.
Slides 5 and 6 show the play BUY is looking at - a mirror image of offshore Guyana which has yielded significant new discoveries.
BUY is running technical due diligence on the asset now.
(source)
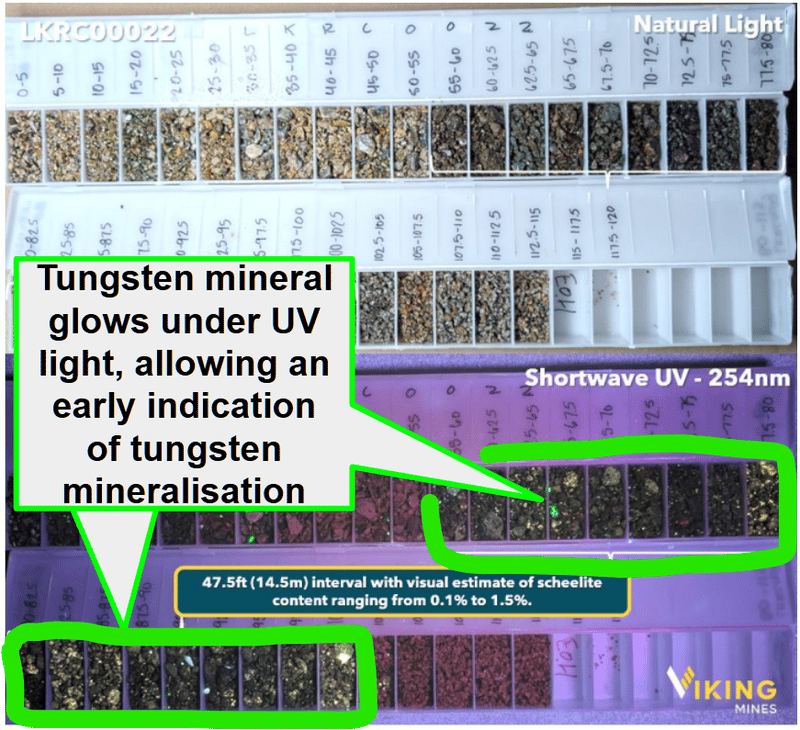
VKA hit more visible tungsten days after restarting Nevada drilling.
These visuals came from the first two holes drilled since the rig returned to site last week.
The best was a 14.5m continuous interval of visible scheelite from just 16.8m downhole (scheelite is a mineral that contains tungsten, and it glows under UV light).
Assays are now pending for another seven holes, expected before the end of this month.
Here are those glorious cores glowing under UV light:
(source)
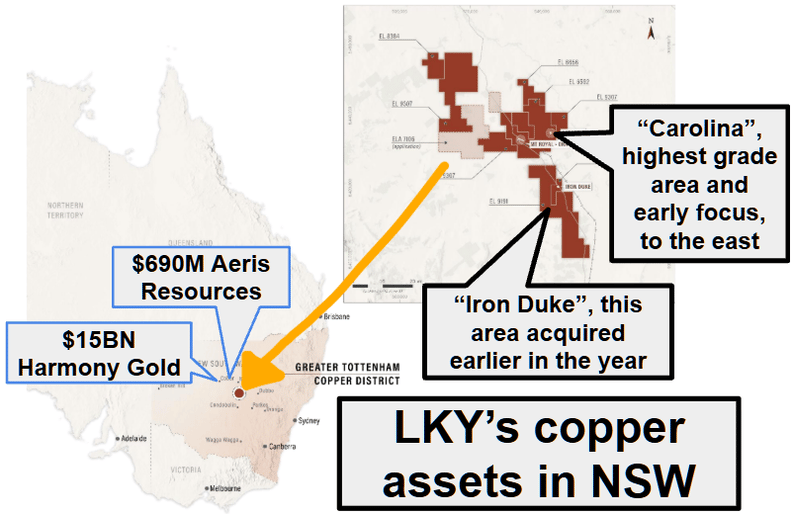
LKY began technical work at its NSW copper project - drilling later this year.
LKY's copper projects already host a combined ~11.2Mt of resources at ~0.7-1% copper, based on old JORC standards.
AND sit in the same part of NSW as $690M Aeris Resources and the Cobar copper operations owned by $15BN Harmony Gold.
LKY has an enterprise value below $10M - not bad for a company with existing copper resources.
(source)
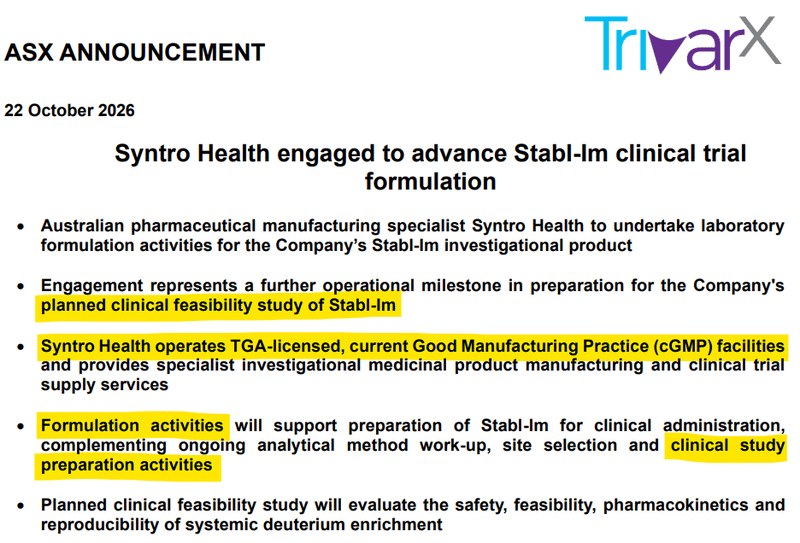
TRI engaged a pharma manufacturer ahead of its Phase 1 brain imaging trial.
TRI is trying to solve the "early detection" problem in brain cancer.
TRI’s technology involves patients swallowing a small dose of a non-radioactive stable isotope which allows for cancer activity to be seen by MRI much earlier than the current standard of care.
(plus without any surgeries OR radiation)
Syntro Health will do the lab formulation work, getting TRI's compounds ready to be administered to patients.
The Phase 1 safety trial is expected to begin before the end of the year, with first patient enrolment scheduled for early next year.
(source)
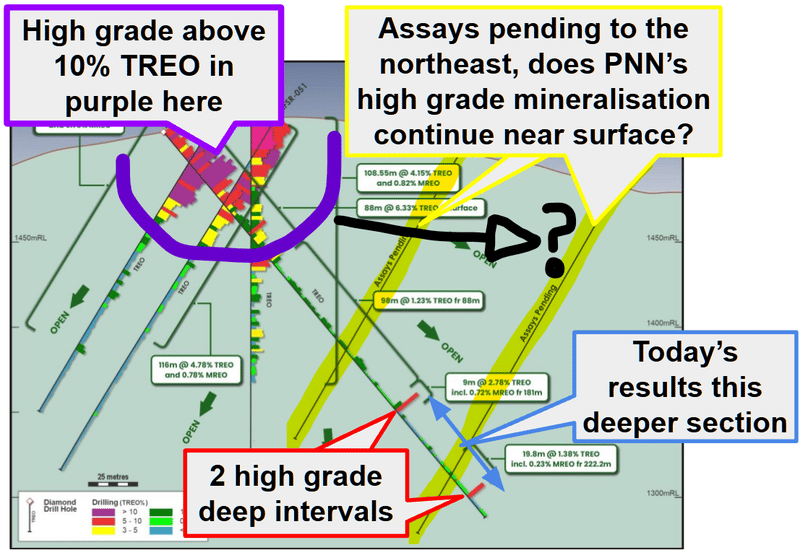
PNN hit its deepest rare earths yet at its Brazil project.
The final assays from hole 54 came back.
That’s the hole that ended in mineralisation at depth, and we were waiting to see if the hole would continue in high grade rare earths.
It wasn’t extremely high grade (relative to the amazing hits PNN has been drilling) BUT it was around 1% TREO (total rare earth oxides) - still pretty decent.
What we are watching now are holes 61 and 65, drilled along the same line to the northeast, which should show whether there is lateral extent to the mineralisation.
All this drilling is feeding into a maiden JORC resource estimate targeted for this quarter or early next year.
(source)
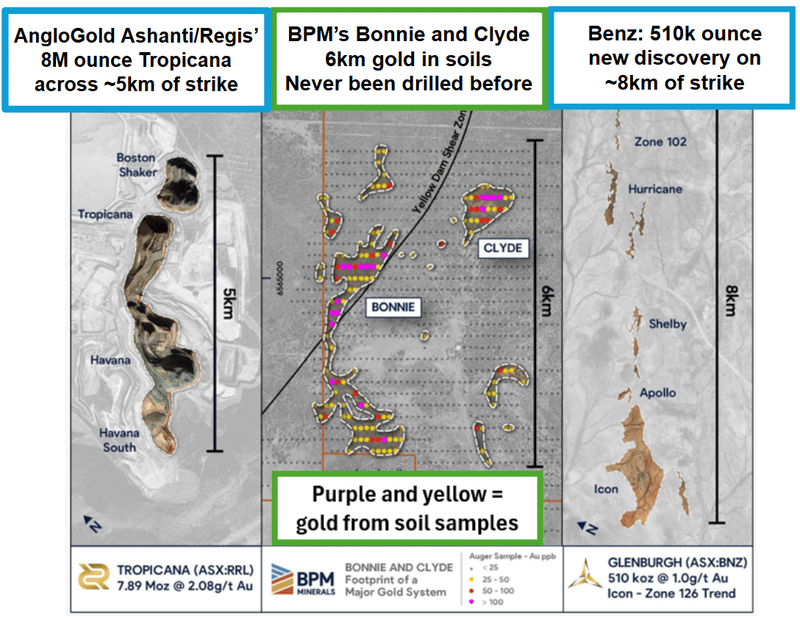
BPM is back drilling its giant Bonnie & Clyde gold target - assays from November.
BPM has now drilled 21 holes into its Bonnie & Clyde targets.
Those are the targets where BPM has a 6km long gold-in-soil anomaly in the same geological setting as the 8Moz Tropicana deposit, owned by $65BN AngloGold Ashanti.
BPM started drilling in mid-September, so it's been over a month drilling - meaning we could get assays from the first few holes any day now.
Fingers crossed we get a trading halt in the next week or so bearing good news... no guarantees of course.
Interesting that the first holes have hit zones of alteration, veining and sulphides - all potential gold hosts.
BPM said assays are due throughout November through to January.
(source)
NS1 launched its first new product under its defence strategy.
NS1's tech securely streams video, voice and data in real time over almost any network, even congested or degraded satellite and cellular links, using minimal bandwidth.
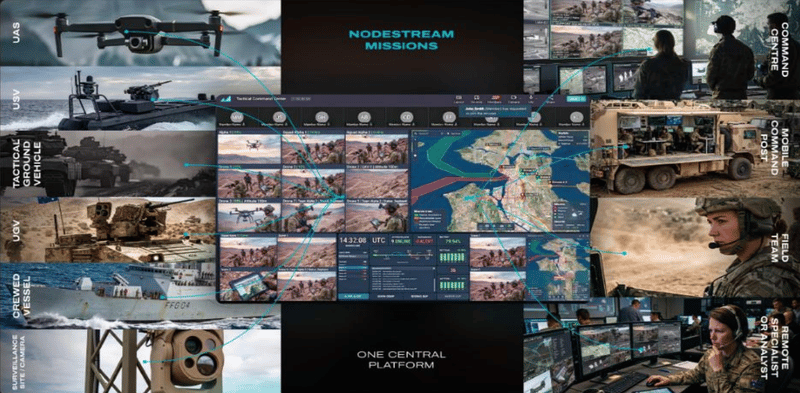
NS1’s new product "Missions" goes live this weekend, pulling live video, audio and data from devices in the field into one central, browser based workspace.
It is the first product delivered under "Plan Consilience", the defence focused strategy NS1 set back in June this year.
Interesting NS1 is offering it as a tiered subscription with unlimited users on every plan - we like this model as it may allow NS1 to drop the price to get its tech in front of more users, then collect the recurring revenue once users see the use case.
(source)
Power Minerals (ASX:PNN)
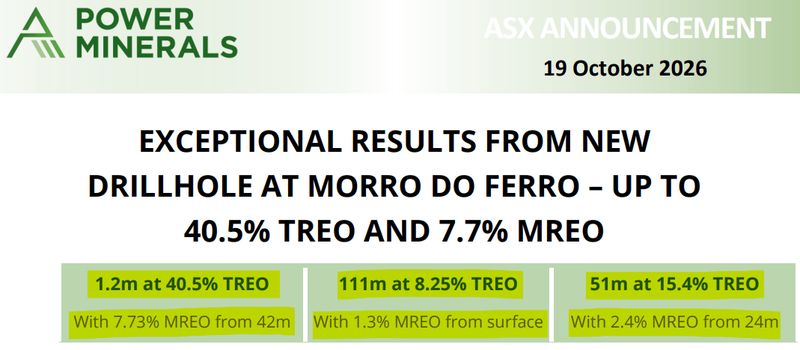
On Monday our Investment PNN hit the best drill result we have seen from any rare earths company on the ASX.
Numbers that only one or two other rare earths deposits anywhere in the world could replicate.
PNN is capped at just $60M... a fraction of its peers.
Here is the drill hit:
(source)
Yes, that is not a typo...
15m at 20.4% TREO with 3.0% MREO
51m at 15.4% TREO with 2.43% MREO
All sitting inside a 111m thick intercept averaging 8.3% TREO and 1.28% MREO from surface.
As we mentioned above, these are drill hits that only one or two other rare earths deposits anywhere in the world could replicate.
One of them is the ~US$6.8BN capped MP Materials' Mountain Pass mine in California - the USA's ONLY producing rare earths mine.
The other is the ~$475M capped Brazilian Rare Earths' Monte Alto deposit, and as the company name suggests, like PNN, it's also in Brazil.
PNN is capped at just $60M.
Both of those bigger companies have deposits with an ultra high grade resource at >10% TREO.
MP's Mountain Pass is ~19Mt at ~7% TREO - and it is the cornerstone asset for the US government's rare earths national champion.
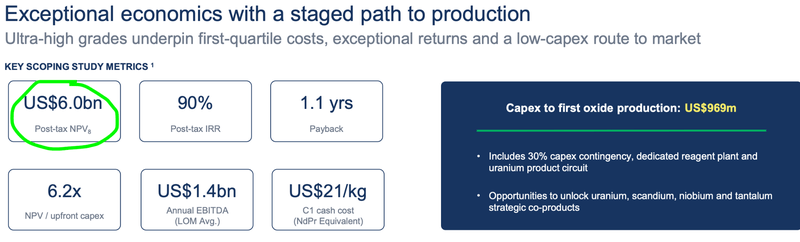
Brazilian Rare Earths' deposit is much smaller, but it's a higher grade - 3.4Mt at 11.26% TREO.
BUT that grade is high enough to deliver a scoping study with a Net Present Value (NPV) of ~US$6BN.
(source)
Which brings us to the other thing we noticed when we put PNN and Brazilian Rare Earths’ cross sections next to each other.
Brazilian Rare Earths’ high grade rare earths mineralisation sits in thin, steeply dipping pods of hard rock, under ~30-40m of cover. Its scoping study plans to drill, blast and selectively mine them on 2m benches. (source)
PNN’s high grade hits start at surface, run 100m+ down every hole, and more than 80% of the drill core is soft, weathered saprolite - the geologists cut it with a steel blade. (source)
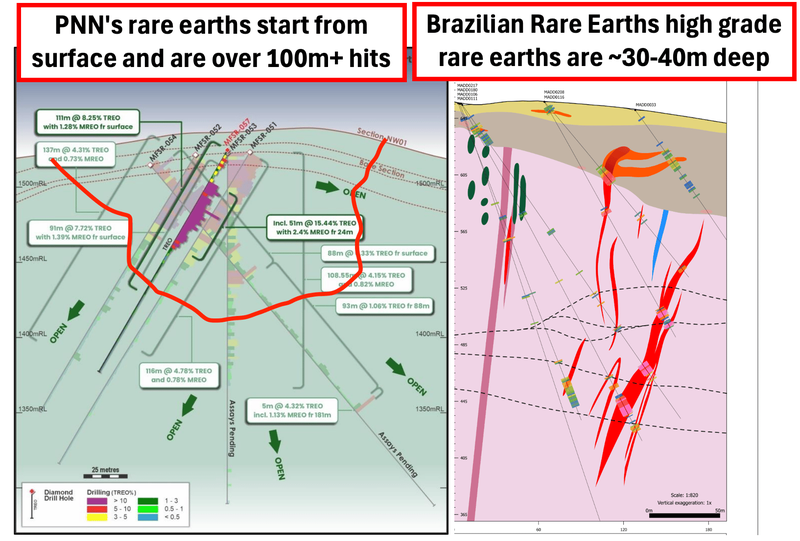
We are not mining engineers, and PNN hasn’t done any official mining or economic studies yet - but on face value, one of those looks a lot simpler and cheaper to dig than the other.
Yep, it's PNN’s.
Right now, PNN’s project has an exploration target of 9.2 - 10.7Mt at 7.8% - 9.2% TREO.
Interestingly, PNN’s high grade hits this week were NOT included in its exploration target model that generated the numbers above.
The upper end of PNN’s exploration target (IF converted into a JORC resource estimate) would put it right up there with the current resource Brazilian Rare Earths has.
Remember Brazilian Rare Earths is capped at $475M, MP Materials at $6.8BN and PNN at $61M.
And now, PNN has intercepts with grades materially higher than the average grade for both those deposits.
Of course, comparing a single intercept to a whole of deposit average shouldn’t be done.
The point for us is that, IF/WHEN PNN can put together its own JORC resource estimate, with grades above OR comparable to the two assets mentioned above, the market COULD then start to reasonably compare PNN’s asset to its peers.
PNN has a maiden JORC resource estimate coming this quarter or next...
Read more: PNN: 51m at 15.4% TREO from 24m - the best rare earths hit we have ever seen on the ASX
Rapid Critical Metals (ASX:RCM)
Has silver found a new base around US$55-60 per ounce?
When silver hit ~US$120 in January it very clearly felt like hot money getting long too hard, too fast.
Now it feels like most of that hot capital has left the building...
And any stragglers left over are being cleaned up BEFORE what we think will be a more sustainable run based on fundamental demand for silver.
We could be wrong, but it feels like we haven’t seen the top of the cycle in silver yet.
The current pullback could just be the reset that every single other major silver bull market has had in the past:
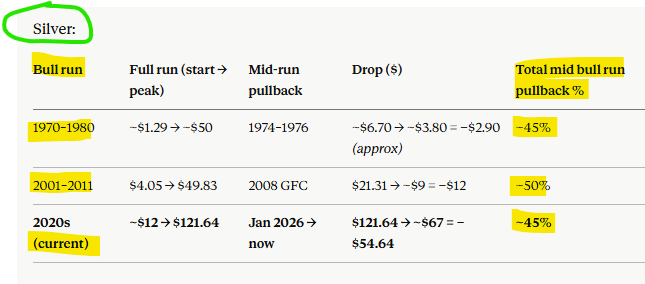
(source: our article from June 2026)
(We still haven't had the “I’m a silver stock now” part of the cycle where almost every ASX micro cap stock acquires a silver asset to get a re-rate in its share price.)
We think the stocks that are already sitting on silver assets with defined resources BEFORE that rally happens could perform the best if/when the silver price runs.
One of those in our Portfolio is RCM.
RCM currently has an estimated 67 million ounces of silver equivalent resources across all its NSW silver projects.
RCM has three drill rigs on site with a fourth one expected to arrive on site very soon, with the goal to grow the silver equivalent resource base.
RCM is targeting a total resource base of 100M oz silver equivalent.
This week’s set of drill results extended one of RCM’s three deposits by ~100m to the north - a good sign for RCM trying to grow that project's resource.
RCM also has an interesting looking critical minerals (gallium / germanium) asset in Canada that is fully permitted and ready to drill - more on this asset in the link below.
Right now, RCM is trading at 2.5c - well below our Initial Entry Price of 3.5c.
3.5c is the same price billionaire silver investor Eric Sprott, and resources funds Tribeca and Jupiter Asset Management invested at.
The RCM share price has now come back to the levels it was trading at when silver was ~US$20 per ounce lower than where it is today:
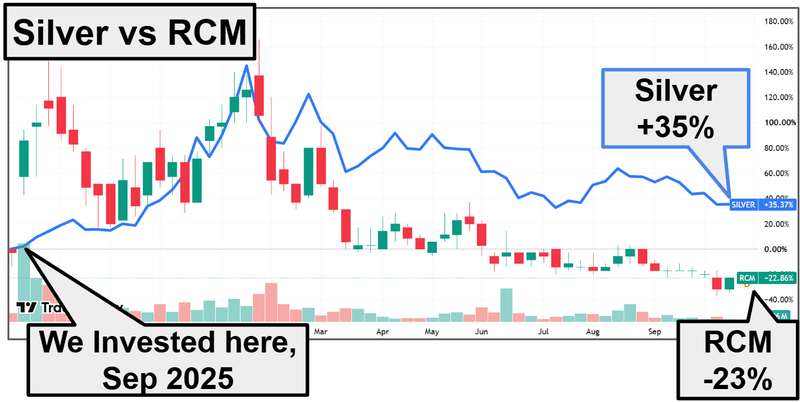
(source)
The past performance is not and should not be taken as an indication of future performance. Caution should be exercised in assessing past performance. This product, like all other financial products, is subject to market forces and unpredictable events that may adversely affect future performance.
Even though fundamentally, a lot has changed with RCM in the last ~12 months.
Especially after this week’s silver drill results. More on what’s changed in the link below.
Read more: RCM: Backed by billionaire precious metals legend Eric Sprott... in his PA account
Peak Processing (ASX:PKP)
THC is the primary psychoactive compound found in cannabis that makes you “high”.
Daily THC use in the USA has now overtaken alcohol.
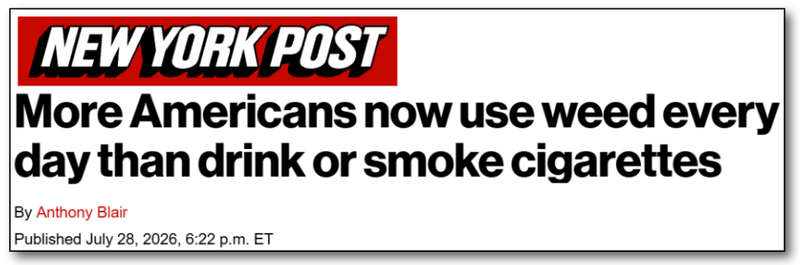
(source)
It looks like our “THC to replace alcoholic drinks” (or even just put a big dent in market share) thesis for Investing in PKP is gaining more traction.
PKP specialises in the manufacturing, sales, and distribution of THC beverages.
PKP is the #1 THC drink manufacturer in Canada - making ~33% of all THC cans in the country.
This week PKP confirmed it entered the “THC shots” market in recent months - specifically 65 mL single-serve shots containing 10mg of THC.
Sales of THC shots have taken off since the July launch of the product with ~87,456 shots produced in the September 2026 quarter.
PKP’s projection is to grow production to ~1M shots per annum (nearly triple the first quarter production run rate).
Shots retail for C$3.95 to C$4.00 each. PKP has not disclosed gross margins as they are commercially sensitive.
PKP owns and sells technology to "infuse any drink with THC” and then manufacture those drinks at scale.
PKP’s THC-infusion can be applied to ANY drink, so any big alcohol company OR drink maker can use PKP to make a non-alcoholic, THC-infused version of their popular brands.
Think THC-infused teas, seltzers, and mocktails.
We Invested in PKP to see it take its market leadership position in Canada and apply it to the much bigger US market.
And because we think there is a longer term macro trend playing out where people would prefer to drink something else other than alcohol socially.
Mainly to avoid that morning after hangover, reduce calorie and sugar intake, and the health risks of ethanol.
BUT still having something to loosen up with on a Saturday night.
It looks like this trend is really starting to happen now.
According to an article a few weeks ago in PBS News, one of the biggest groups backing THC drinks in the US is... yep... alcohol retailers:
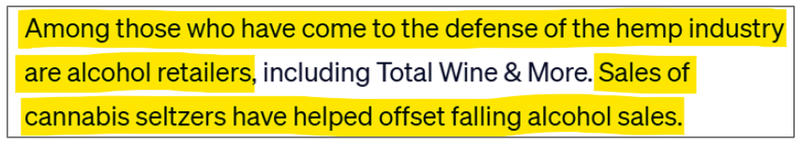
(source)
In the government's eyes - regulation is heading the same way the alcohol industry is regulated:
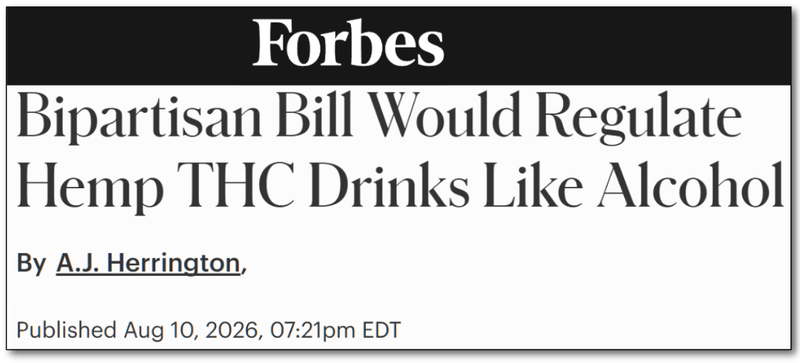
(source)
Read more: PKP is making THC shots now - looks like they are a hit with consumers
Lodestar Minerals (ASX:LSR)
ASX small caps are taking a beating... for now.
(blame tax changes, house prices, interest rates, etc etc)
BUT...
It turns out WA gold producers are printing cash at today's gold prices.
And when cashed up miners are met with beaten down smaller stocks - it usually means it’s M&A time.
(M&A = Mergers and Acquisitions)
WA gold miners sold a record $36 billion worth of gold back in 2025. (source)
That was in a year where gold averaged US$3,400 per ounce.
Gold has been above US$4,000 per ounce for almost all of 2026 - so this year could be even bigger for WA’s gold producers.
In the last few months we have seen:
- Genesis and Vault agreed to merge into a $12.6 billion gold miner
- $8.8BN OceanaGold paying $776 million for Ausgold
- $830M Forrestania launched a $93.5 million bid for Zenith
So... WA gold assets are in demand - even when broader sentiment for small caps is pretty terrible.
Which is why we think our micro cap Investment Lodestar Minerals’ (ASX:LSR) announcement this morning may get some interest from the market.
This week LSR delivered a maiden 221,000 ounce at 1.16 g/tonne gold JORC resource estimate for its WA gold project.
“Within trucking distance” of multiple gold processing plants - including $1.4BN Catalyst Metals’ “underutilised” plant ~40km away.
(underutilised... meaning a potential home for LSR’s resource)
Mineralisation remains open at depth and along strike, and LSR is planning on follow up drilling this quarter.
LSR also announced a new exploration target for up to ~264k additional ounces which, if converted into a JORC resource could take LSR’s total resources up near the ~500k ounce level.
LSR is capped at ~ $10M, and in addition to its WA gold asset, also has some interesting Chilean copper and USA rare earths exploration assets.
(more on the other assets in the link below - a big copper discovery would be pretty handy right now)
This week’s announcement was all about the WA gold asset:
Minbos Resources (ASX:MNB)
We have been Invested in Minbos Resources (ASX:MNB) for six years.
(at 3c, 8c, 11c, 7c and most recently 1.5c)
We Invested to see them build a phosphate (fertiliser) mine and processing plant in Angola (global food security thematic).
There were a few years in a row where the company was signalling:
“We have almost secured financing” and
“We are about to build the plant and start selling fertiliser".
A project that according to MNB's 2022 Definitive Feasibility Study was supposed to generate ~US$55M in EBITDA per year over a 20 year mine life, with a post-tax NPV of US$203M. (source)
However we note that MNB’s development plan has changed since that study - MNB simplified the plant flowsheet in late 2025 - so these numbers could be different now.
We only use the study as a basis for what the project could look like.
But the promised build didn't happen on time...
and the market stopped trusting what MNB promised = share price went down a lot.
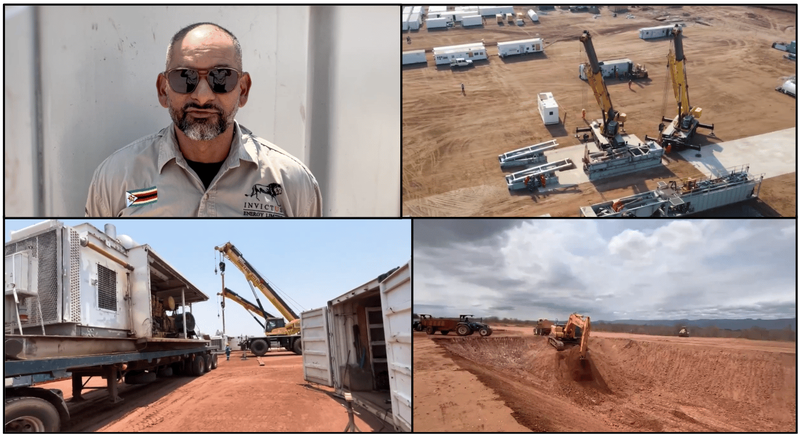
It looks like the long promised and awaited plant build is finally happening... and fast:
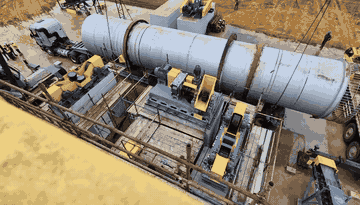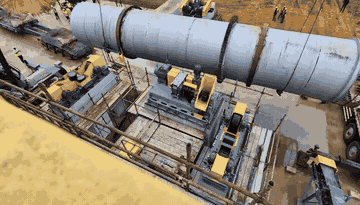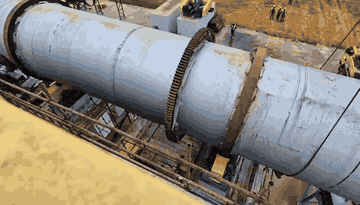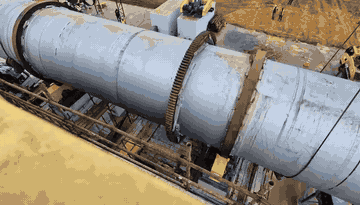
A rotary dryer getting hoisted up at MNB site - it removes the moisture from the mined phosphate rock
In just the last three months MNB has gone from this:
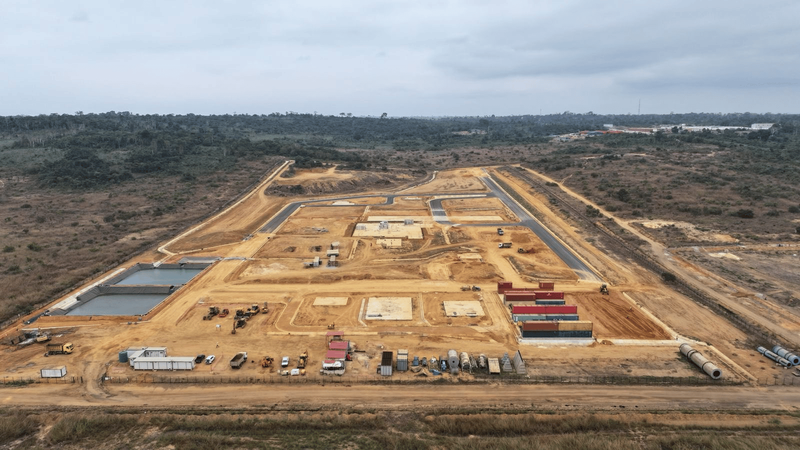
To this:
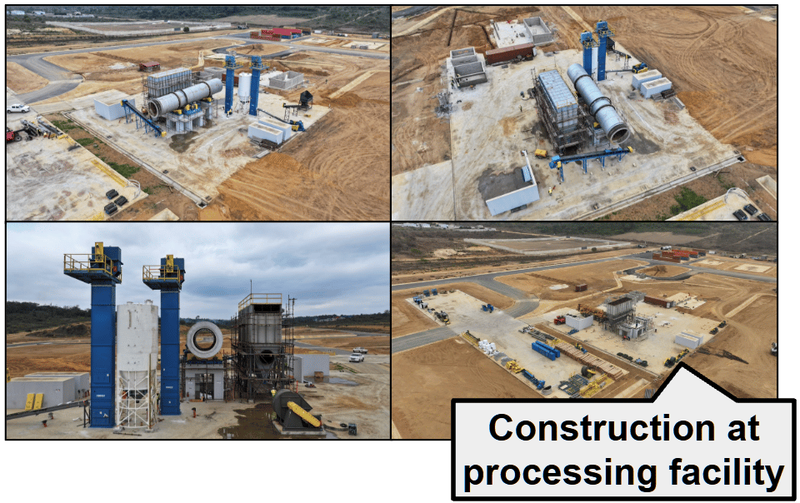
And here is where MNB is at relative to what it is supposed to look like when it's finished:
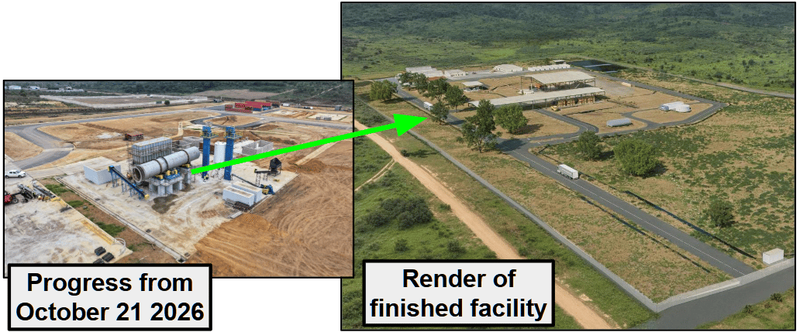
(source - MNB socials)(source)
Hard to argue with that visual progress... even for the most sceptical long term MNB followers.
IF MNB can deliver the timelines its saying, we should see:
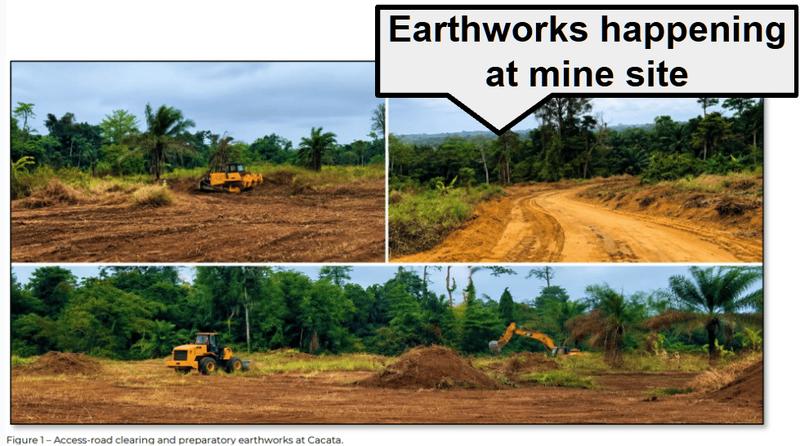
- Mine mobilisation "in H2 2026" - Earthworks started two weeks ago so on a technicality we could say this one has happened. (source)
- A Ministerial site visit "scheduled in December" to inspect the completed plant structures. (source)
- And the plant "on track for completion and dry commissioning in Q2 2027" - subject to financing, deliveries and approvals. (source)
(long suffering MNB holders don't have much trust in MNB’s timeline predictions, and rightly so - but we haven’t seen them make this much progress in previous attempts so maybe these timelines will finally be the real deal)
Once in production, MNB will own Angola's first and only integrated phosphate mine and fertiliser plant.
Read more: MNB: It looks like they are actually building it (finally)
Bloomberg - Trump's Mineral Stockpile Prepares Up to $1 Billion in Loans
Micron - Micron Invests in New York Critical Minerals Processing With Indium Corporation
We Invested in AW1 because it has the largest indium JORC resource estimate within the USA. So it’s good to see indium processing, and its use cases get some attention. Indium processors will need ore supply in the chain.
Reuters - US holds more secret talks with Myanmar's military-backed rulers in Tokyo, sources say.
FT - Japan ‘months’ from running out of critical rare earth as China squeezes supply
WSJ - The Most Polite Trucker in America Is a Driverless 18-Wheeler
FT - The battle of the knee replacement robots
TechCrunch - Tesla starts Optimus robot production in California as profit falls 43%
Bloomberg - Unitree founder now expects robots breakthrough as soon as 2028
S&P Global - West must mobilize to narrow China's minerals lead: Friedland
InvestorNews - Scandium: Can New Supply Keep Pace With Defense and AI?
Mining.com - AI boom could overwhelm metals supply: WoodMac
Mining.com - US moves to unlock deep-sea minerals near American Samoa with massive auction
FT - Are we sleepwalking into World War III?
Bloomberg - Daily Pill to Keep Breast Cancer Away Is Roche's Next Frontier Drug
Bloomberg - Nigeria Reports First Ebola Case in Traveler From Uganda
ScienceDaily - Rejuvenation breakthrough: Scientists reverse 60 years of aging in human cells
AFR - BHP vows to double Australian copper output by 2040
Bloomberg - Ghana to End Unprocessed Mineral Exports by 2030, President Mahama Says
MINMIDT - MINIM-MARTAP BAUXITE PROJECT: STEADY PROGRESS RECORDED ACROSS PROJECT SITES
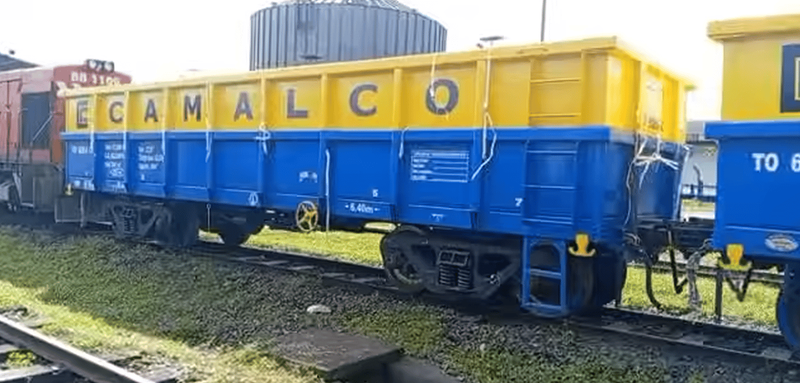
Good to see progress appears to still be continuing at CAY’s project with this from the Cameroon Ministry of Mines, Industry and Technological Development website (MINMIDT).
That article included this video showing the wagons in country and moving on rails
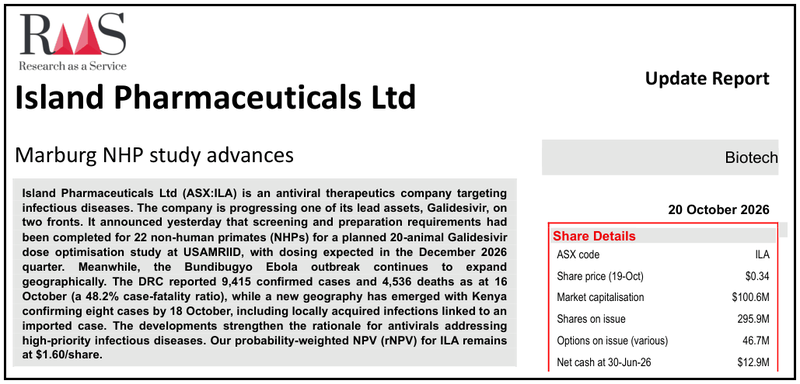
ILA - Marburg NHP study advances - RAAS
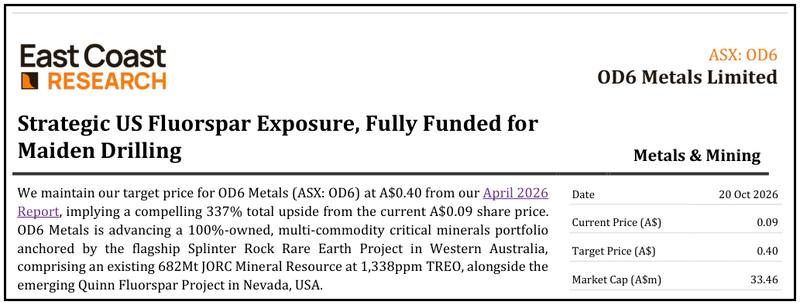
OD6 - Strategic US Fluorspar Exposure, Fully Funded for Maiden Drilling - East Coast Research
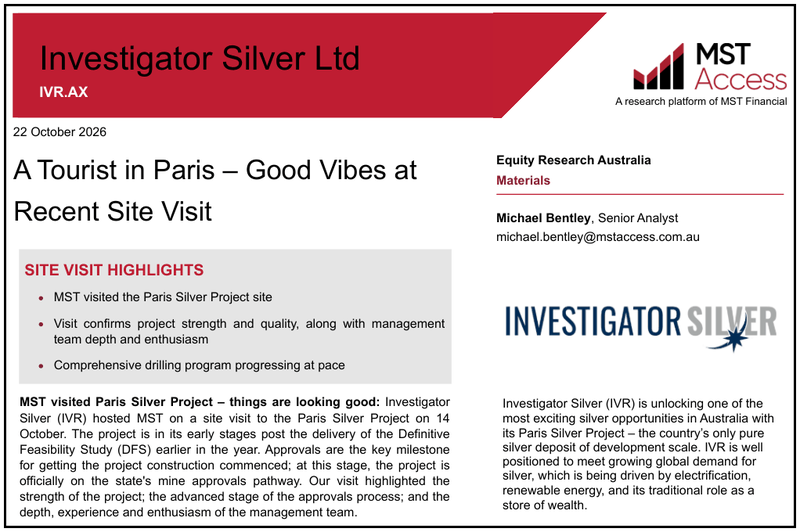
IVR - A Tourist in Paris - Good Vibes at Recent Site Visit (Update Report) - MST Financial
AL3 - Build faster, stronger and greener with ARCEMY
BUY - Low Risk Production Company with Transformational Offshore Exploration
PNN - 111m @ 8.25% TREO From Surface. Why Is Power Minerals Not at New Highs? - Alistair Stephens ASX: PNN (CEO interview)
RCM - Rapid’s record silver grades point to more potential at Webbs (MD interview)
NS1 - Nodestream Webinar - October 16, 2026 (Webinar)
ILA - Biotech & Healthcare Webinar Series | The Infection Playbook (Webinar)
LSR - Significant Maiden Gold Resource Puts Lodestar's Ned’s Creek in Focus (CEO interview)
LSR - Lodestar eyes growth beyond 221,000 ounces of gold at Ned’s Creek (CEO interview)
AVM - Advance Metals (ASX:AVM) - Explore the Gavilanes Silver-Gold Project in 3D (3D project visualisation)
Robots - Flying Tesla Car, Robot Brains Halving in Cost Every 3 Weeks, and Why Incentives Decide AI Alignment (Peter H. Diamandis)
Energy - The Great Oil Split Has Begun || Peter Zeihan (Zeihan on Geopolitics)
IVZ - Drilling preparations are ramping up ahead of a targeted November spud, some more images of the move in progress here:
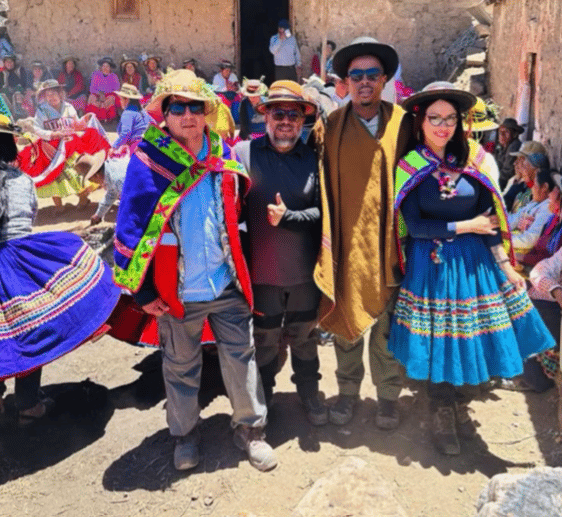
PAT - Joined its local community's farming season celebrations in Peru:
PKP - CEO Barry Katzman to moderate a cannabis supply chain conference panel:
LKY - Opening a new chapter of copper exploration in central NSW at the Greater Tottenham project, sharing a brief overview and flyover:
A word of caution...
While we aim to highlight developments in the small cap space, investing in early-stage and small cap companies - like those we cover - is inherently risky.
These companies often face funding challenges, regulatory hurdles, and market volatility. Announcements may reflect aspirations more than guaranteed outcomes.
Things can, and often do, change.
Just because a company has signed a deal, released drill results, or appointed a new director doesn’t mean success is assured.
Always assume delays, cost overruns, or results that don’t pan out.
We’re here to share insights, not offer personal financial advice - so please do your own research and speak with a licensed adviser before acting on anything mentioned.
Follow us on social media: X, LinkedIn, Facebook
Bye for now.
General Information Only
This material has been prepared by StocksDigital. StocksDigital is an authorised representative (CAR 000433913) of 62 Consulting Pty Limited (ABN 88 664 809 303) (AFSL 548573).
This material is general advice only and is not an offer for the purchase or sale of any financial product or service. The material is not intended to provide you with personal financial or tax advice and does not take into account your personal objectives, financial situation or needs. Although we believe that the material is correct, no warranty of accuracy, reliability or completeness is given, except for liability under statute which cannot be excluded. Please note that past performance may not be indicative of future performance and that no guarantee of performance, the return of capital or a particular rate of return is given by 62C, StocksDigital, any of their related body corporates or any other person. To the maximum extent possible, 62C, StocksDigital, their related body corporates or any other person do not accept any liability for any statement in this material.
Conflicts of Interest Notice
S3 and its associated entities may hold investments in companies featured in its articles, including through being paid in the securities of the companies we provide commentary on. We disclose the securities held in relation to a particular company that we provide commentary on. Refer to our Disclosure Policy for information on our self-imposed trading blackouts, hold conditions and de-risking (sell conditions) which seek to mitigate against any potential conflicts of interest.
Publication Notice and Disclaimer
The information contained in this article is current as at the publication date. At the time of publishing, the information contained in this article is based on sources which are available in the public domain that we consider to be reliable, and our own analysis of those sources. The views of the author may not reflect the views of the AFSL holder. Any decision by you to purchase securities in the companies featured in this article should be done so after you have sought your own independent professional advice regarding this information and made your own inquiries as to the validity of any information in this article.
Any forward-looking statements contained in this article are not guarantees or predictions of future performance, and involve known and unknown risks, uncertainties and other factors, many of which are beyond our control, and which may cause actual results or performance of companies featured to differ materially from those expressed in the statements contained in this article. S3 cannot and does not give any assurance that the results or performance expressed or implied by any forward-looking statements contained in this article will actually occur and readers are cautioned not to put undue reliance on forward-looking statements.
This article may include references to our past investing performance. Past performance is not a reliable indicator of our future investing performance.