$10M capped LSR now has a 221k ounce JORC gold resource - 40km away from $1.4BN WA gold producer Catalyst Metals
Disclosure: S3 Consortium Pty Ltd (the Company) and Associated Entities own 34,846,000 LSR Shares and 26,627,263 LSR Options at the time of publishing this article. The Company has been engaged by LSR to share our commentary on the progress of our Investment in LSR over time. This information is general in nature about a speculative investment and does not constitute personal advice. It does not consider your objectives, financial situation, or needs. Any forward-looking statements are uncertain and not a guaranteed outcome.
ASX small caps are taking a beating... for now.
(blame tax changes, house prices, interest rates, etc etc)
BUT...
It turns out WA gold producers are printing cash at today's gold prices.
And when cashed up miners are met with beaten down smaller stocks - it usually means it’s M&A time.
(M&A = Mergers and Acquisitions)
WA gold miners sold a record $36 billion worth of gold back in 2025. (source)
That was in a year where gold averaged US$3,400 per ounce.
Gold has been above US$4,000 per ounce for almost all of 2026 - so this year could be even bigger for WA’s gold producers.
In the last few months we have seen:
- Genesis and Vault agreed to merge into a $12.6 billion gold miner
- $8.8BN OceanaGold paying $776 million for Ausgold
- $830M Forrestania launched a $93.5 million bid for Zenith
So... WA gold assets are in demand - even when broader sentiment for small caps is pretty terrible.
Which is why we think our micro cap Investment Lodestar Minerals’ (ASX:LSR) announcement this morning may get some interest from the market.
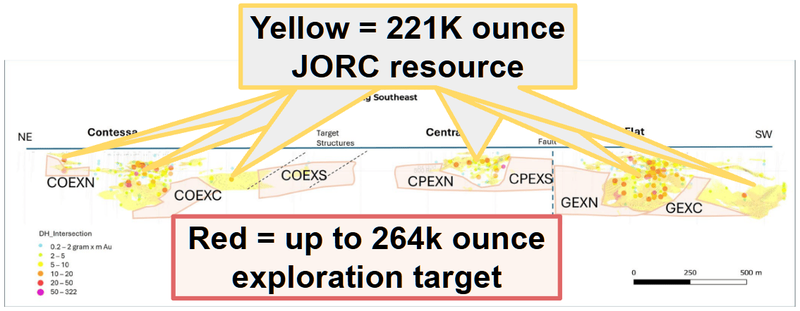
🚨THIS MORNING, LSR delivered a maiden 221,000 ounce at 1.16 g/tonne gold JORC resource estimate for its WA gold project.
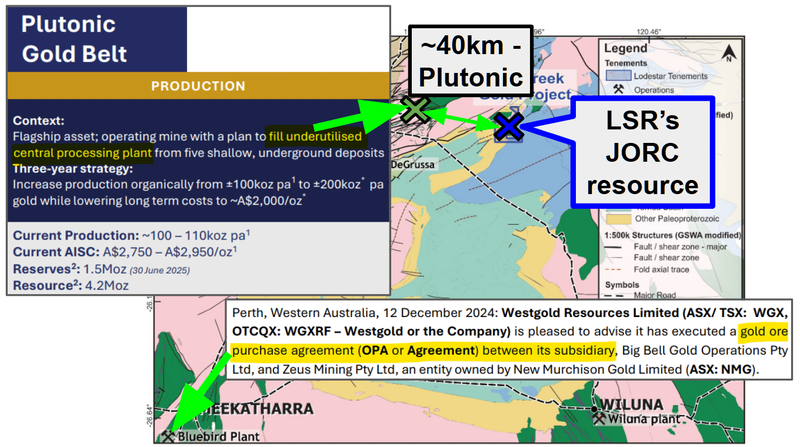
“Within trucking distance” of multiple gold processing plants - including $1.4BN Catalyst Metals’ “underutilised” plant ~40km away....
(underutilised... meaning a potential home for LSR’s resource)
Mineralisation remains open at depth and along strike, and LSR is planning on follow up drilling this quarter.
LSR also announced a new exploration target for up to ~264k additional ounces which, if converted into a JORC resource could take LSR’s total resources up near the ~500k ounce level.
LSR is capped at ~ $10M, and in addition to its WA gold asset, also has some interesting Chilean copper and USA rare earths exploration assets.
(more on the other assets later - a big copper discovery would also be pretty handy right now)
Today’s announcement is all about the WA gold asset...
Here is how LSR’s WA gold resource (and exploration target) looks visually:
(source)
The idea is that LSR can just drill in/around the current resource and that JORC resource should grow.
LSR’s gold resource sits within “trucking distance” of multiple mills including:
- (The closest to LSR) $1.4BN Catalyst Metals' gold mine - Catalyst has been on the record saying the plant is “underutilised and centrally located” AND previously did a deal to toll-treat up to ~250ktpa of third party ore back in February this year. (source) (source)
Fun fact: Catalyst actually paid ~A$32.5M cash for another deposit ~40km away from its mine not that long ago - see that here. - $4.9BN Westgold's mill - Westgold did an “ore purchasing agreement” with another WA gold stock - New Murchison Gold - which has since rallied from ~$66M market cap to over $600M (past performance not an indicator of future performance of LSR).
- Wiluna Mining’s mill - Wiluna just completed a $470M IPO (it starts trading today), and has been very public about capacity at its mill for third party ore - although we are aware that mill is currently not operating.
Being close to a mill means no matter how big a resource, the chances of the project getting developed is stronger (relative to projects in remote areas).
Especially when the resource is below the ~1M ounce level (which is psychologically the level the ASX starts to really re-rate explorers).
(Probably the level where the ASX believes the resource is big enough to warrant building a new processing plant).
LSR’s resource isn't at the ~1M ounce level BUT at current gold prices, even small gold resources can re-rate stocks IF they have access to processing infrastructure.
For example:
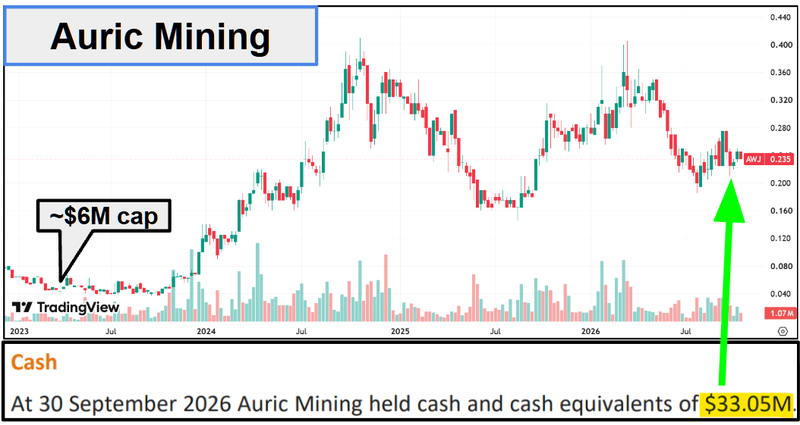
Auric Mining which was capped at ~$6M in March 2023.
AND has since produced ~35-40k ounces of gold all using third party processing infrastructure.
Auric now has a market cap of ~$44M and has ~$33M cash at 30 September 2026. (source)
The past performance is not and should not be taken as an indication of future performance. Caution should be exercised in assessing past performance. This product, like all other financial products, is subject to market forces and unpredictable events that may adversely affect future performance.
Another is New Murchison Gold which was capped at $66M in November 2024.
New Murchison took a ~279,000 ounce resource started mining it in September 2025 and sells the ore to $4.9BN Westgold.
New Murchison had $220.4M cash at 30 September 2026 and is now capped at ~$650M. (source)
(New Murchison also just declared its first ever dividend today - congrats to any holders there)
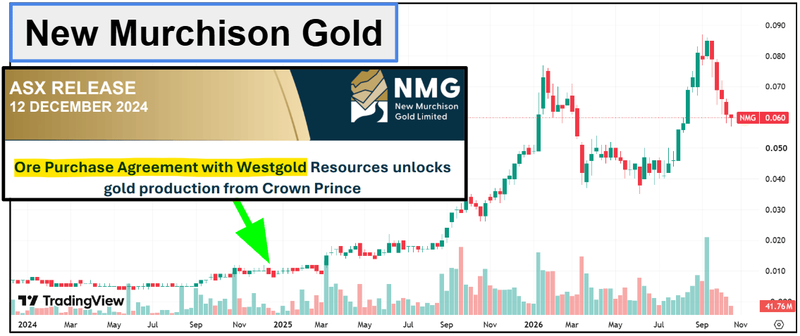
The past performance is not and should not be taken as an indication of future performance. Caution should be exercised in assessing past performance. This product, like all other financial products, is subject to market forces and unpredictable events that may adversely affect future performance.
Interestingly - that New Murchison deal was with the mill that LSR’s resource is not too far away from:
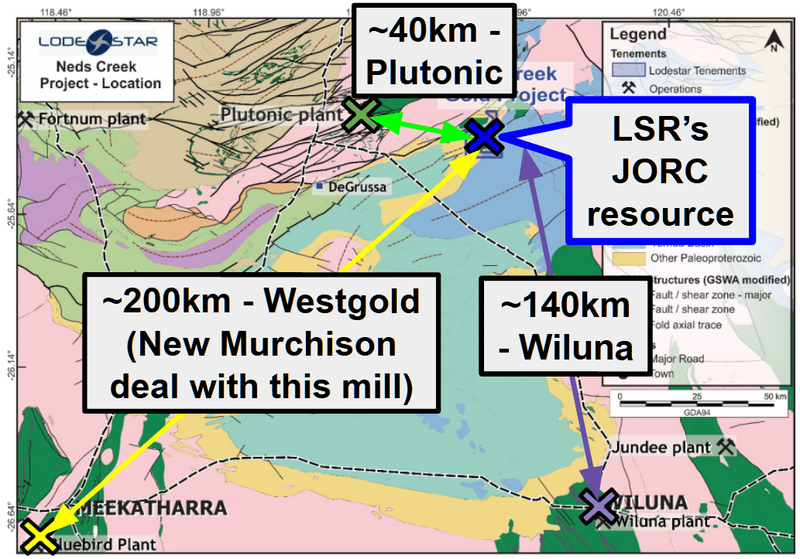
(source)
We are not saying LSR will do the same thing, BUT these are lived examples for the ASX of how a nearby mill makes a potentially stranded asset economically viable...
LSR now trading at only $30 EV/ounce of gold metric
At LSR’s current price of 0.7c, the company is capped at ~$10.4M.
LSR had $3.5M cash at 30 June 2026 - but this will likely be lower when the September quarterly comes out before the end of the month. (source)
Using that June cash balance, LSR's enterprise value is ~$7M.
So based on its current 221,000 ounce gold resource, LSR is trading at an EV/ounce ratio of ~A$30.
EV/ounce is a pretty conventional/well understood way the market is able to value JORC resources on the ASX.
The higher the gold price, the higher that metric usually gets.
For context - Western Gold Resources, which had previously signed a toll-treatment deal with Wiluna Mining’s mill, has a ~277k ounce resource and trades at a ~$72 EV/gold ounce ratio.
It’s understandable why Western Gold’s ounces are valued higher, given it has a toll treatment deal and therefore a clearer pathway to revenue - LSR has more work to do on this front, but the pathway for LSR is fairly clear - get its Mining Lease sorted and then try to negotiate a toll treatment deal.
That $30/oz on LSR is assuming the market is putting ZERO value against LSR’s three copper projects in Chile AND its US rare earths project.
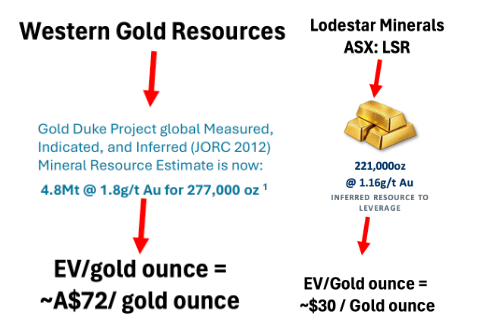
Whilst LSR has some work ahead of it, the positive in the short term for LSR will be that the gold resource will put somewhat of a floor under its valuation (where the market is happy to support the stock should that EV/ounce ratio get lower).
WHICH we think might give LSR an increased ability to raise cash at less dilutive share prices, and drill test its “swing for the fence” exploration targets in Chile and USA.
Speaking of swing-for-the-fences exploration...
LSR has three copper exploration projects in Chile - all pre-discovery, all chasing deposits similar in style to the giant Candelaria mine, owned by the ~$28BN Lundin Mining.
(Candelaria is one of the biggest copper-gold mines in Chile)
Here is a quick overview of each one:
- Three Saints - LSR drilled this one earlier in the year confirming a copper system BUT no major discovery as yet. The next step for this one is to reprocess geophysical data and refine drilling locations for its next drill program.
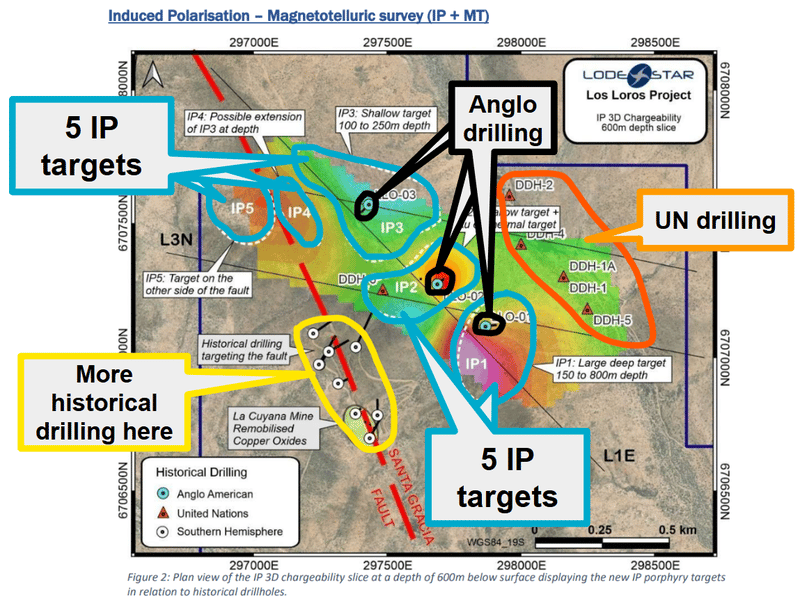
- Los Loros - On this project, LSR has 5x porphyry targets defined through geophysical surveys. LSR was supposed to be drilling there in July, but this was delayed due to weather. So this drilling could start any day now... (source)
- Pacifico - The most recent project acquisition from August. This project has historical drilling data with 16 holes and peak grades of up to 1.03% copper equivalent. LSR wants to drill this one in Q2-2027 (so still a fair bit of work to do here). (source)
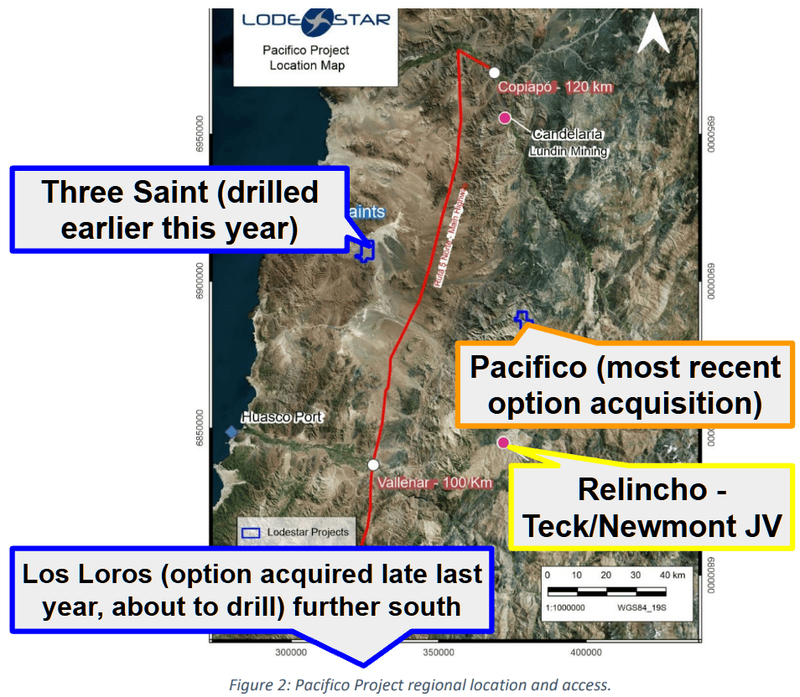
(source)
Right now it looks like the next one to be drilled will be Los Loros.
Here are the five targets from that project:
(source)
Check out our Deep Dive on Los Loros here.
LSR also has a US heavy rare earths exploration project
The main reason we first Invested in LSR was for its US heavy rare earths project.
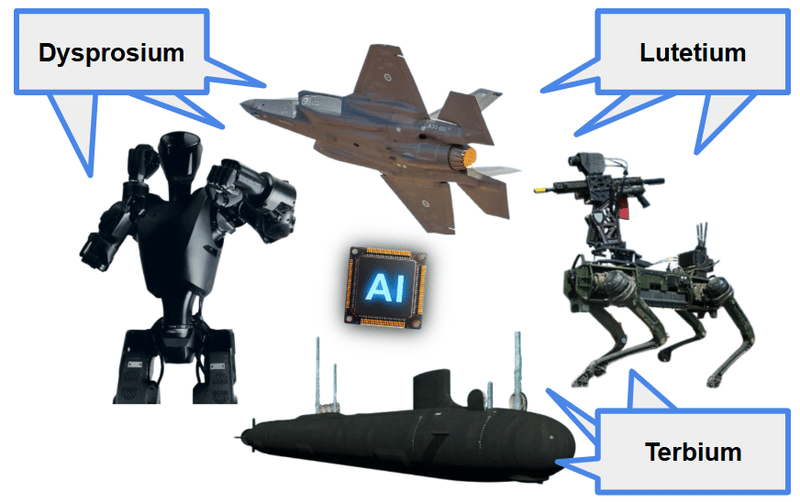
LSR's Virgin Mountain project in Arizona contains high-grade heavy rare earths like dysprosium, terbium and lutetium.
The type of rare earth elements that the US needs the most... but has very little of.
All three are on the US critical minerals list, and all three are export-controlled by China.
Dysprosium, terbium and lutetium are used to produce:
- Artificial Intelligence (AI)
- AI-driven defence
- Autonomous war robots and drones
- Quantum computing, and
- Advanced energy technologies.
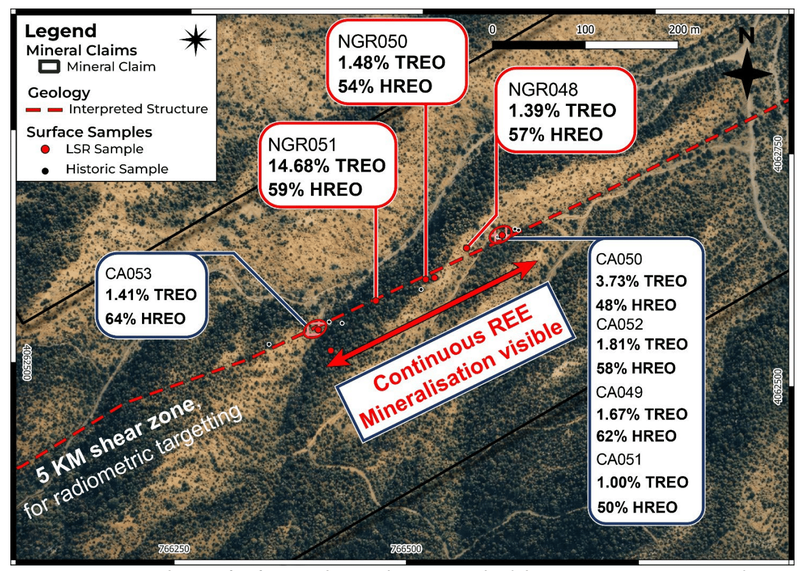
LSR's USA project has rock chip samples up to 14.68% TREO, with heavy rare earths making up as much as 64% of the rare earths in the samples - across a ~275m sampled trend within a ~5km interpreted structural trend.
(source)
Earlier this year, LSR announced that mineralogy testing showed the rare earths are hosted in "xenotime" - a well-known rare earth host mineral that the west understands and can extract with conventional processing.
(unlike most rare earth projects, which are more like "chemistry experiments" to try and economically extract the goodies)
🎓 We wrote about why the market cared about that here: LSR: Dysprosium, terbium and lutetium in xenotime... huh? The market liked it.
One of the main reasons we Invested in LSR was because we think the US, which already has light rare earth production coming from the ~$10BN MP Materials' Mountain Pass mine in California, will need domestic heavy rare earth feedstock.
MP is building a magnet plant in Texas literally called the "10X" facility.
And MP has built a heavy rare earth separation circuit at its mine in California that is designed to process third-party feedstock - MP has said it is "actively engaging emerging suppliers" and plans to integrate several sources over time.
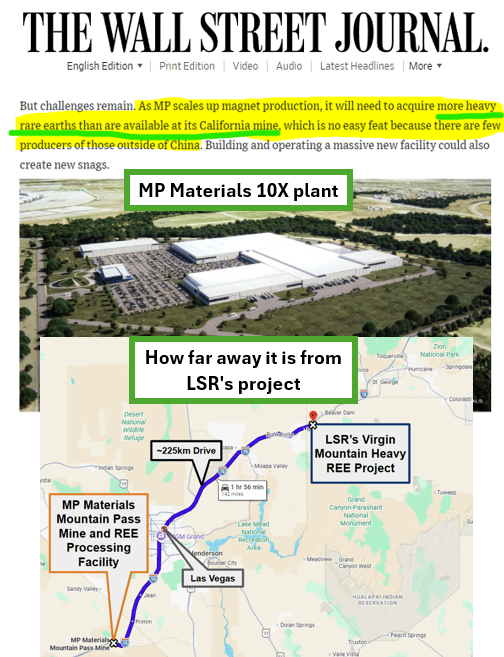
We think the urgency inside the US on this stuff recently went up a notch, post the Iran war starting.
So, IF LSR's project shows any signs of size/scale it could become a strategically important asset inside US borders.
Again, it's worth noting that at this stage it is still very early days for this project - we really need to see it drilled to find out if anything potentially economic sits on it.
Here is a LinkedIn update from the LSR team on site at the project:
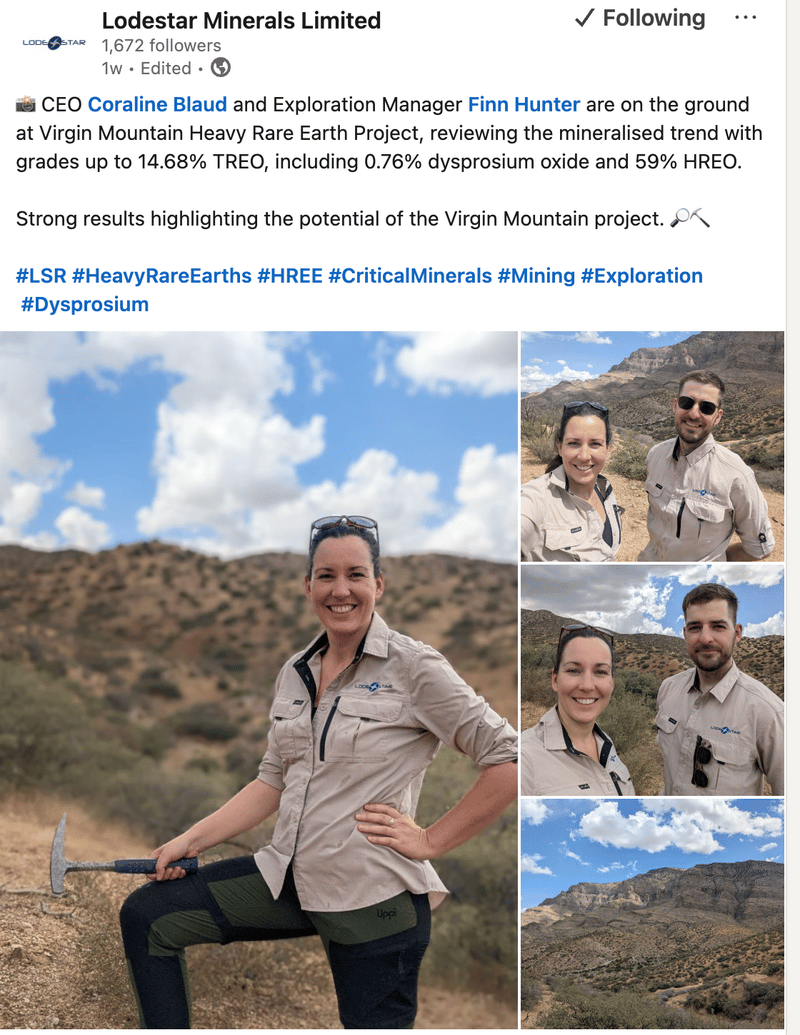
(source)
LSR has started a technical review of the project too (precursor to drill permitting) - so we are hopefully slowly getting closer to first drilling on this asset too.
Ultimately we want to see LSR drill all of its exploration assets because you never know what sits below the rocks above ground... AND our Big Bet is based around LSR having exploration success as follows:
Our LSR Big Bet:
"LSR makes an economic discovery on its US heavy rare earths projects and re-rates 1,000% from our Initial Entry Price"
NOTE: our "Big Bet" is what we HOPE the ultimate success scenario looks like for this particular Investment over the long term (3+ years). There is no guarantee that our Big Bet will ever come true. There is a lot of work to be done, many risks involved, including development risk, country risk and commodity price risk - just some of which we list in our LSR Investment Memo.
Success will require a significant amount of luck. Past performance is not an indicator of future performance.
What we want to see next from LSR
🔄 Chile copper drilling
LSR has three projects in Chile - Three Saints, Los Loros and Pacifico.
Next we want to see LSR drill its Los Loros project - here are the milestones we are tracking for that project:
🔲 Access road reinstated / drilling date confirmed
🔲 Drilling underway
🔲 Assay results
✅ Progress on WA gold project
Now that LSR has its maiden resource estimate, we want to see LSR progress the project closer to being development ready.
Here are the milestones we are tracking on that project now:
✅ Drilling complete
✅ Assay results
✅ Maiden JORC resource estimate
🔲 Metallurgical test work results
🔲 Mining Lease application (targeted early 2027)
🔲 Processing deal
🔄 Target generation on the US rare earths project
We want to see LSR continue to advance its US asset through the technical review and then plan the first drilling.
Here are the milestones we are tracking for the US asset:
✅ Mapping and sampling (soil and rock chips)
✅ Mineralogical studies
🔄 Geophysics / follow up field work (radiometric survey + ground follow up)
🔲 Drill targets confirmed
🔲 Drill permitting
What could go wrong?
The single biggest risk right now is without a doubt commercialisation risk for the WA gold project.
Having a resource is one thing, developing it and making it a mine is another.
LSR’s resources could be considered too small to justify LSR building its own processing infrastructure.
That means the realistic path into production runs through someone else's mill - and there is no guarantee LSR gets access to one.
The second major risk is “Exploration risk”.
LSR is about to drill one of its copper projects right now, there is no guarantee LSR discovers anything economically viable - if that were to happen LSR’s share price could move lower.
Other risks
Like any early-stage exploration company, LSR carries significant risk, here we aim to identify a few more risks.
LSR is a pre-revenue micro-cap needing to fund exploration programs across Australia, Chile, and the US - this will likely require future capital raises, presenting dilution risk for existing shareholders.
Advancing these projects requires clearing several key regulatory hurdles, including securing a WA Mining Lease targeted for early 2027 and obtaining US drilling permits.
Any bureaucratic, environmental, or stakeholder delays could push timelines back and inflate holding costs.
Investors should consider these risks carefully and seek professional advice tailored to their personal circumstances before investing.
Our LSR Investment Memo
You can read our LSR Investment Memo in the link below.
We use this memo to track the progress of all our Investments over time.
In our LSR Investment Memo you'll find:
- What does LSR do?
- The macro theme for LSR
- Our LSR Big Bet
- What we want to see LSR achieve
- Why we are Invested in LSR
- The key risks to our Investment Thesis
- Our Investment Plan
General Information Only
This material has been prepared by StocksDigital. StocksDigital is an authorised representative (CAR 000433913) of 62 Consulting Pty Limited (ABN 88 664 809 303) (AFSL 548573).
This material is general advice only and is not an offer for the purchase or sale of any financial product or service. The material is not intended to provide you with personal financial or tax advice and does not take into account your personal objectives, financial situation or needs. Although we believe that the material is correct, no warranty of accuracy, reliability or completeness is given, except for liability under statute which cannot be excluded. Please note that past performance may not be indicative of future performance and that no guarantee of performance, the return of capital or a particular rate of return is given by 62C, StocksDigital, any of their related body corporates or any other person. To the maximum extent possible, 62C, StocksDigital, their related body corporates or any other person do not accept any liability for any statement in this material.
Conflicts of Interest Notice
S3 and its associated entities may hold investments in companies featured in its articles, including through being paid in the securities of the companies we provide commentary on. We disclose the securities held in relation to a particular company that we provide commentary on. Refer to our Disclosure Policy for information on our self-imposed trading blackouts, hold conditions and de-risking (sell conditions) which seek to mitigate against any potential conflicts of interest.
Publication Notice and Disclaimer
The information contained in this article is current as at the publication date. At the time of publishing, the information contained in this article is based on sources which are available in the public domain that we consider to be reliable, and our own analysis of those sources. The views of the author may not reflect the views of the AFSL holder. Any decision by you to purchase securities in the companies featured in this article should be done so after you have sought your own independent professional advice regarding this information and made your own inquiries as to the validity of any information in this article.
Any forward-looking statements contained in this article are not guarantees or predictions of future performance, and involve known and unknown risks, uncertainties and other factors, many of which are beyond our control, and which may cause actual results or performance of companies featured to differ materially from those expressed in the statements contained in this article. S3 cannot and does not give any assurance that the results or performance expressed or implied by any forward-looking statements contained in this article will actually occur and readers are cautioned not to put undue reliance on forward-looking statements.
This article may include references to our past investing performance. Past performance is not a reliable indicator of our future investing performance.